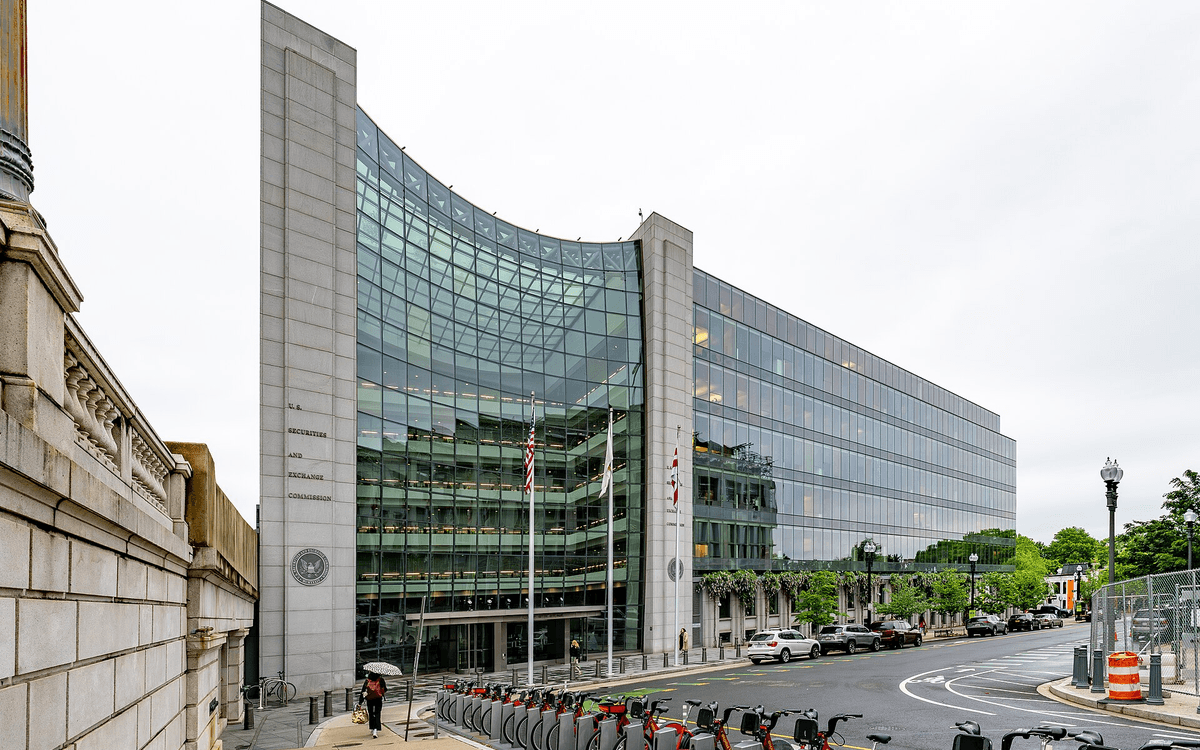
The U.S. Securities and Exchange Commission proposed rewriting public-company executive pay disclosures on 13 November 2026. The plan would narrow the standard group of executives whose compensation is reported and raise the threshold for reporting executive perks fifteenfold. It is a proposal, not a final or effective rule. Companies must follow their existing disclosure obligations while the regulator considers comments.
The overhaul targets Item 402 of Regulation S-K, whose framework was last comprehensively reformed in 2006. Its central question is whether simpler filings help investors identify important pay arrangements or instead remove useful comparisons. The SEC favours less repetitive reporting, while investor advocates worry about diminished transparency.
Key facts
- The SEC announced proposed amendments on 13 November 2026; no final rule has been adopted.
- The named-officer group would generally shrink from five or more executives to two.
- The aggregate threshold for reporting executive perquisites would climb from $10,000 to $150,000.
- A 60-day comment period begins after publication of the proposal in the Federal Register, not automatically on the announcement date.
Who and what would still be disclosed?
The proposal would generally identify the principal executive officer and principal financial officer - normally the chief executive and chief financial officer - as the named executive officers. Other senior managers commonly included today would no longer appear in the primary named-officer comparisons at many companies. That would not prohibit a company from giving investors more information voluntarily.
Four core compensation tables would become three: the Earned Compensation Table, Granted Compensation Table and Status of Equity Awards Table. Narratives would accompany those tables. Rather than merely removing numbers, the SEC says it wants investors to see how equity awards move through the stages of grant, earning and continuing status. Whether the redesign improves comparability is disputed.
The proposed $150,000 threshold refers to the aggregate disclosure of perquisites, not a tax exemption, a permitted salary supplement or a government-mandated benefit. The plan would add a small-benefit tracking exclusion and give companies greater latitude to judge, reasonably and in good faith, what qualifies as a perk. A higher threshold and more judgment mean that a shareholder could see less itemized information about management benefits.
The employee pay ratio and performance measures
The changes extend beyond executives' headline salaries. For the median employee used in chief-executive-to-worker pay-ratio reporting, companies would consider U.S. full-time workers and determine that median once every five years. That is narrower than the present approach described by the SEC. It could alter reported ratios at companies employing large international or part-time workforces, without necessarily reflecting any change in their actual pay.
Pay-versus-performance reporting would also become simpler. The SEC proposes replacing the complex Compensation Actually Paid calculation with earned compensation from the proposed new table and reducing mandatory performance measures. Compensation Discussion and Analysis would address three required subjects rather than a rule listing fifteen illustrative subjects. Separate annual-report checkboxes and overlapping disclosures about clawbacks would be dropped, although the underlying company clawback mechanisms would remain unchanged.
Chairman Paul Atkins presents this as a move toward materiality, informed by more than 80 comment letters after the agency's 2025 compensation roundtable. The SEC claims it would ease compliance burdens, but its 13 November release does not establish a measured dollar saving.
An independent Reuters report on 13 November quoted Better Markets securities-policy director Ben Schiffrin criticizing the likely loss of investor visibility. His organization's claims about long-run CEO and worker compensation are advocacy claims, not findings established by the SEC. A separate Journal of Accountancy report confirmed the proposal's principal table, officer and perquisite changes.
What happens before any company changes its proxy?
The SEC must collect and assess comments and decide whether to adopt, revise or abandon the amendments. Its announced consultation lasts 60 days after Federal Register publication; an exact deadline cannot be calculated from the press-release date alone.
For investors, the practical trade-off is between shorter standardized filings and less mandatory visibility into executives beyond the top two. For issuers, the possible benefit is simpler preparation, not permission to stop reporting now. Until a final rule takes effect, the announcement changes neither an executive's pay nor the disclosure requirements governing the next proxy statement.