The British government promised on 16 November 2026 to legislate for access to essential face-to-face banking services, accepting the central recommendation of an independent review commissioned by the Treasury. The announcement is a commitment to develop legal protections, not an enacted rule or an immediate ban on closing bank branches.
The review, chaired by Richard Lloyd, examined whether declining access to staffed banking causes consumer harm. It drew on more than 18,000 responses from members of the public and evidence supplied by businesses, charities and consumer organisations. The central policy distinction is between being able to withdraw cash and being able to obtain personal help with an account or a difficult financial problem.
What the promised protection would mean
Treasury says the framework should preserve essential in-person banking for people who need it. The review describes two categories: day-to-day services, centred on opening and managing a personal current account, and more complex services for customers dealing with unusual circumstances or needing tailored support. Neither category has yet been converted into a binding definition or a specified distance from a customer's home.
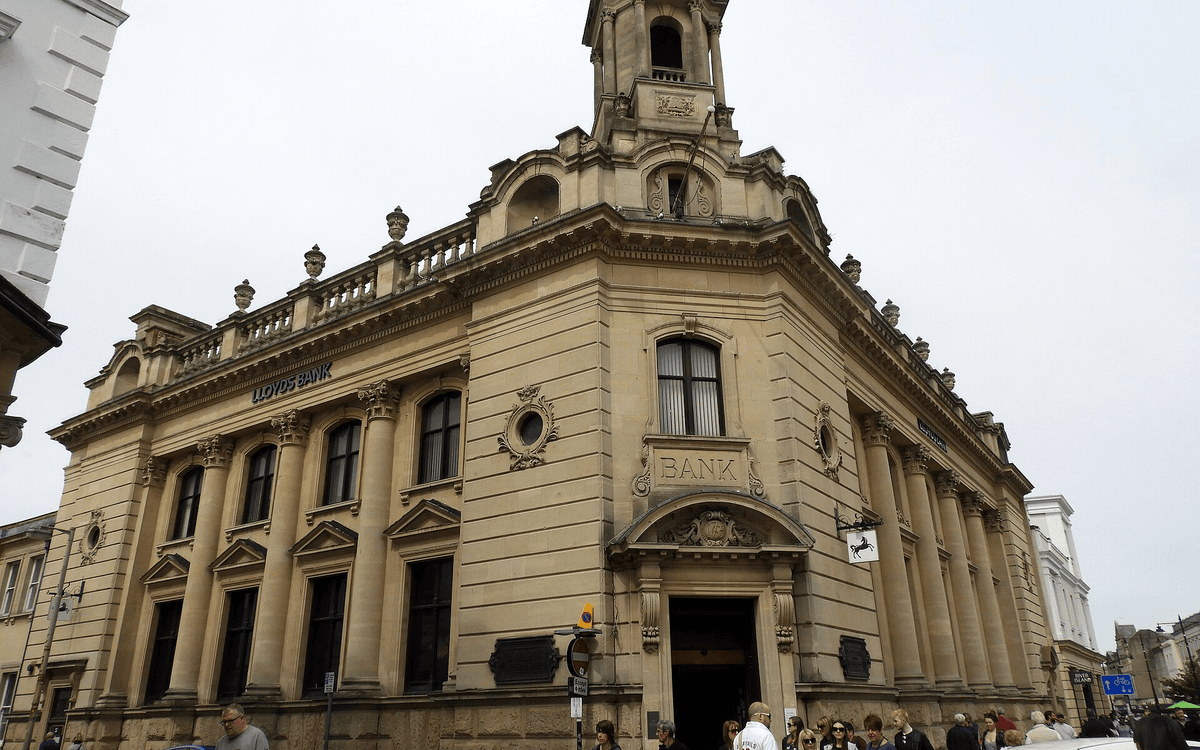
That matters because a cash machine, shared banking hub and fully staffed bank branch do not offer exactly the same service. A customer might be able to deposit money locally but still struggle to correct an account problem or speak with someone about a sensitive change in personal circumstances. Equally, protecting a service does not necessarily mean requiring each bank to keep every existing branch. The government has not yet decided where that boundary should fall.
More than three million adults regularly rely on banking in person, according to the review evidence described by Treasury. Including less frequent users lifts the estimate above four million. The report identifies particular barriers for older and disabled people, people on low incomes, customers with limited digital access and those experiencing major life changes. These groups overlap; the estimates are not a count of people who never use online banking.
The Treasury will consult the Financial Conduct Authority, banks, consumer groups and other stakeholders on the detailed framework and what constitutes reasonable access. No implementation date, nationwide service-distance standard or enforcement arrangement was announced on Monday.
The existing rules cover a narrower problem
The Financial Conduct Authority already supervises access to cash facilities and provides a process for considering significant changes to local withdrawal and deposit services. Its consumer guidance explains how communities can raise concerns about cash access. Those arrangements do not amount to a general statutory guarantee that someone can open an account in person or obtain specialist help from a bank employee.
Banking habits are changing at the same time as the physical network contracts. Treasury cites FCA data showing that 79.6% of the population lived within three miles of a physical branch operated by a major provider in 2025, against 87% in 2022. These are population coverage percentages rather than branch totals; the measure also cannot establish whether public transport or disability access makes a nearby branch usable.
The Treasury announcement also cites the FCA's 2024 Financial Lives Survey, which found that 75% of day-to-day account holders used a mobile banking app in the preceding twelve months. Yet 26% of consumers said they found it difficult or impossible to reach the right person to resolve a query across channels. Widespread adoption of apps therefore does not eliminate the need for human assistance.
Key facts
- 16 November 2026: the government accepted the review's principal recommendation and promised legislation, but has not enacted the new framework.
- More than three million: estimated regular users of face-to-face banking, increasing beyond four million when occasional users are counted.
- 79.6% versus 87%: estimated population within three miles of a major provider's physical branch in 2025 compared with 2022.
- Two types of need: routine current-account services and more complicated, personalised support are the review's starting points.
The next step is to define which services must be available in person, who must provide them, how availability will be measured and how a rule would be enforced. Until legislation is developed and takes effect, today's pledge changes the government's policy direction rather than the immediate legal position of a particular bank or customer.